Canada’s Productivity Tax Break Puts Pressure on Trump’s Trade Strategy — But the “War-Footing” Claim Needs Context
Canada has unveiled one of its most aggressive business-investment tax changes in decades, expanding immediate tax deductions for companies investing in machinery, technology, infrastructure, energy and other capital assets.
Prime Minister Mark Carney announced the Productivity Mega Deduction on September 15 at Canada’s first Canada Investment Summit, presenting it as a way to attract investment and strengthen the Canadian economy amid continuing trade tensions with the United States.
The measure is significant: Canada says it will reduce the marginal effective tax rate on new business investment from roughly 13% to 6.4%, compared with 16.9% for the United States under the government's comparison.
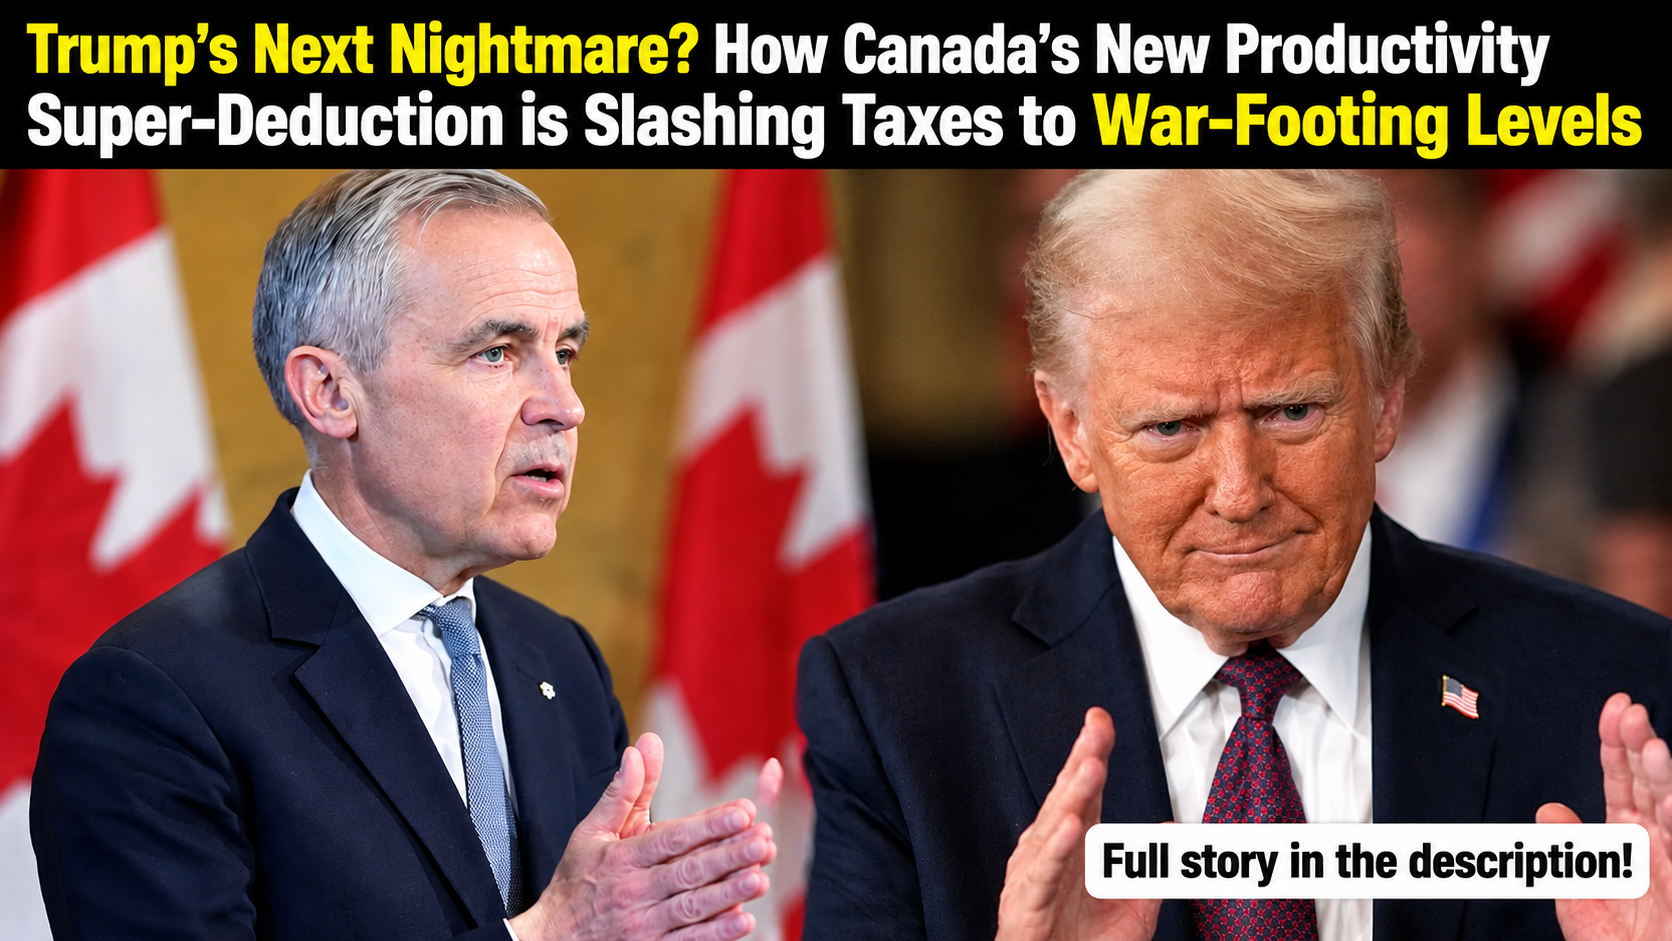
But the viral image's description of this as pushing Canadian taxes to “war-footing levels” is rhetorical rather than a literal description of Canada's tax system. The 6.4% figure is a measure of the tax burden on a marginal new investment, not the overall corporate tax rate or the amount companies pay on all income.


What exactly is the Productivity Mega Deduction?
The new policy builds on Canada's Productivity Super-Deduction, introduced in Budget 2025.
Previously, the super-deduction provided immediate expensing for roughly 15% of investment in capital assets, including certain manufacturing machinery, clean-energy equipment, zero-emission vehicles, patents, computers and data-network infrastructure.
The new Productivity Mega Deduction would dramatically broaden that coverage.
The government says more than 65% of investment in capital assets could become eligible for immediate expensing.
That includes assets such as:
- Fibre-optic cable
- Mining property
- Oil and gas pipelines
- Software
- Research and development
- Computer equipment
- Aircraft and vehicles
- Patents
- Rail tracks
- Bridges
- Roads
- Manufacturing equipment
The government is also proposing to make immediate expensing permanent rather than allowing the incentives to expire after a temporary period.
What does “immediate expensing” actually mean?
This is where the viral graphic can be misleading.
A company that buys a qualifying $10 million piece of equipment normally cannot necessarily deduct the entire $10 million from taxable income in the first year. Under Canada's capital-cost-allowance system, deductions are generally spread over time.
Under immediate expensing, the company can deduct the eligible investment's full cost in the year the asset becomes available for use.
That does not mean the government hands the company $10 million.
Instead, the deduction reduces the company's taxable income and therefore lowers the tax cost associated with making the investment.
Canada's Finance Department describes the policy as a way to reduce the after-tax cost of investment and encourage companies to deploy capital more quickly.
The number attracting the most attention: 6.4%
The headline figure is Canada's projected 6.4% marginal effective tax rate, or METR, on new business investment after the Mega Deduction.
Canada's Finance Department compares that with a 16.9% U.S. METR for 2026.
That is a substantial difference.
| Measure | Canada after Mega Deduction | U.S. 2026 |
|---|---|---|
| Marginal effective tax rate on new investment | 6.4% | 16.9% |
| Canada before new measure | ~13% | — |
| Eligible capital assets | More than 65% | Different U.S. rules |
The comparison is important because METR is specifically designed to measure the tax burden associated with an additional dollar of investment.
It is not the same thing as saying that Canadian companies now have a 6.4% corporate income-tax rate.


Why is Carney making this move now?
The timing is closely connected to Canada's changing economic relationship with the United States.
Canada remains deeply integrated with the U.S. economy, but President Donald Trump's tariff policies have increased uncertainty for Canadian exporters and businesses.
The Bank of Canada has said U.S. trade policy and slower population growth are weighing on Canada's productive capacity. Its May 2026 analysis projected potential-output growth at only 1.2% in 2026, before strengthening as business and government investment recover.
The central bank's July outlook similarly said Canada's productive capacity would grow slowly in 2026 because of tariff-related structural adjustments and subdued population growth. It expects stronger investment, including AI investment, to contribute to productivity later.
Against that backdrop, Ottawa is trying to make investment in Canada more financially attractive.
Canada is trying to turn the trade shock into an investment push
Carney's government says the objective is not simply to cut taxes.
It wants companies to build more factories, mines, energy infrastructure, data centers, transportation infrastructure and technology facilities inside Canada.
The federal government estimates the Mega Deduction will cost approximately C$36 billion over five years, beginning in fiscal 2026-27.
In return, Ottawa estimates that the measure could generate significantly more economic activity over the longer term.
The Finance Department estimates that the roughly C$8.5 billion in average annual investment support could generate between 1.4 and 3 times that amount in additional economic activity over a 10-year horizon, potentially translating into as much as approximately C$22 billion in additional annual output.
Those figures are government estimates, not guaranteed outcomes.
And Canada is targeting C$1 trillion in new investment
The tax reform is part of a much broader investment campaign.
Carney's government has set an objective of catalyzing roughly C$1 trillion in additional investment through public, private and institutional capital.
At the September 15 investment summit, Ottawa also promoted major infrastructure and industrial projects and announced plans to invite private investors to participate in long-term operating concessions for Canada's four largest airports while retaining public ownership.
The strategy is therefore broader than simply reducing business taxes.
It combines:
Tax incentives + infrastructure + energy + critical minerals + technology + private capital + international investment.
Could this affect the U.S.-Canada investment relationship?
Potentially, but it is too early to say how much capital will actually move because of the policy.
Canada's tax advantage is particularly relevant for projects requiring large amounts of upfront capital.
For example, a mining operation, data center, manufacturing facility or energy project may involve billions of dollars in equipment and infrastructure.
Being able to deduct eligible investment immediately can improve the project's after-tax economics and potentially make Canada more competitive when companies compare locations.
Reuters reported that the new policy is intended to attract more than C$1 trillion in investment, particularly in mining, energy, technology and infrastructure, as Canada confronts trade tensions with the United States.
But taxation is only one factor.
Companies also consider:
- Energy costs
- Labor availability
- Infrastructure
- Regulation
- Market access
- Financing costs
- Political and trade stability
- Supply chains
- Proximity to customers
A lower METR therefore does not automatically guarantee that investment will leave the United States for Canada.
Trump remains central to the story
The viral graphic frames the policy as “Trump's next nightmare,” but that is an interpretation rather than a documented reaction from Trump.
There is a factual connection, however.
Canada is pursuing this investment strategy while negotiations over the future of the U.S.-Canada trading relationship remain difficult.
Carney said at the investment summit that Canada would not rush into an agreement with Washington simply to restore the previous trading relationship. The AP reported that he argued Canada could wait for conditions that provide a better basis for a new arrangement.
At the same time, Canada continues to have enormous economic exposure to the United States.
That means the strategy is better understood as economic diversification and increased bargaining resilience, rather than an attempt to replace the U.S. economy overnight.


The productivity problem existed before Trump
Another important piece missing from the viral headline is that Canada's productivity problem predates the current trade dispute.
Canadian policymakers have been concerned for years about weak business investment and labor-productivity growth.
The Bank of Canada's 2026 analysis specifically identifies stronger business investment as an important factor in improving Canada's long-term productive capacity.
The current trade conflict has added urgency, but the underlying problem is older.
That helps explain why Ottawa is presenting the policy as a structural economic reform rather than simply a temporary response to Trump's tariffs.
There are also critics and risks
The government expects the tax incentives to stimulate investment, but the benefits are not guaranteed.
One risk is that companies may receive large tax deductions without generating the scale of additional investment policymakers expect.
Another is that businesses may still hesitate to invest because of weak demand or trade uncertainty.
The Bank of Canada's second-quarter 2026 Business Outlook Survey found that investment intentions remained strong, particularly for productivity-related investments such as equipment upgrades and AI, but lingering uncertainty and soft demand continued to constrain some businesses.
The policy also carries a fiscal cost.
Ottawa estimates the Mega Deduction itself will reduce federal revenues by about C$36 billion over five years.
The government's argument is that the lost tax revenue is an investment in future economic activity that will broaden the tax base and increase productivity.
Whether that trade-off produces the expected returns will depend on how businesses actually respond.
What the viral image gets right — and what it leaves out
What it gets right
The core event is real.
Canada has announced a major expansion of immediate tax deductions for business investment, and the government says the policy will reduce the marginal effective tax rate on new investment to 6.4%.
The measure also comes at a politically important moment, with Canada trying to attract investment while dealing with U.S. tariff uncertainty.
What it leaves out
The phrase “slashing taxes to war-footing levels” is not an official description of the policy.
The 6.4% figure is a marginal effective tax rate on new investment, not Canada's general corporate tax rate.
Nor has the policy been demonstrated yet to have caused a massive investment shift from the United States to Canada.
And although the government projects up to C$22 billion in additional annual economic output over the longer term, that is a forecast based on economic modeling—not money that has already been generated.
So, is this really a “nightmare” for Trump?
The available evidence does not establish that.
What can be established is that Canada is responding to a difficult trade environment by making new investment substantially more tax-competitive.
The policy could make Canada more attractive for certain capital-intensive projects, particularly in sectors such as energy, mining, manufacturing, technology and infrastructure.
At the same time, the U.S. remains Canada's dominant economic partner, and investment decisions depend on far more than tax deductions.
The more consequential question is therefore not whether Canada has suddenly become a low-tax economy across the board.
It is whether a 6.4% marginal effective tax rate on new investment, combined with Canada's energy resources, infrastructure plans and access to international markets, can generate the investment surge Ottawa is targeting.
That answer will only become clearer as companies begin making actual investment decisions under the new rules.
Suggested SEO Setup
SEO Title:
Canada’s New Productivity Mega Deduction Cuts Investment Tax Rate to 6.4%
Alternative Headline:
Trump’s Next Trade Challenge? Canada Unveils Huge New Tax Break for Business Investment
Meta Description:
Canada's Productivity Mega Deduction would cut the marginal effective tax rate on new investment to 6.4%, as Mark Carney seeks C$1 trillion in new investment.
Slug:canada-productivity-mega-deduction-carney-trump-investment
Category:
Canada News / Business & Economy / U.S.-Canada Trade
Tags:
Mark Carney, Donald Trump, Canada, Productivity Mega Deduction, Canadian Economy, U.S.-Canada Trade, Investment, Business Taxes, Canada Investment Summit, Tariffs
Comments (0)
Loading comments...
May You Like
OBAMA STUNS ON INSTAGRAM: MESSAGE MARKING 34-YEAR MILESTONE SPARKS A BUZZ
Barack Obama Draws Attention With New Literary Podcast
South Korea–Ukraine Rift Deepens Over North Korean POW Transfer as PURL Draws New Scrutiny